Listen Now
0:00
Flaws in the federal law governing the Canada Pension Plan (CPP) have left billions of dollars at stake ahead of Monday’s Alberta referendum on separation, with estimates of how much the province could claim from the fund ranging from $150 billion to more than $300 billion.
The CPP was established in 1966 to provide retirement income to older Canadians and fill gaps in private pension coverage. Even before its launch, some members of Parliament were considering the possibility that Alberta might someday create its own pension plan.
Talking Points
- Canada’s chief actuary has described the decades-old formula for calculating a departing province’s share of CPP assets as “flawed”
- Economist Trevor Tombe estimates Alberta could claim between 20 to 25 per cent of CPP assets if the province withdraws from the fund, far below the 53 per cent projected in a provincial government-commissioned report
- Alberta’s withdrawal could raise the minimum CPP contribution rate for Canadians in the rest of the country—except Quebec—by roughly 0.5 percentage points
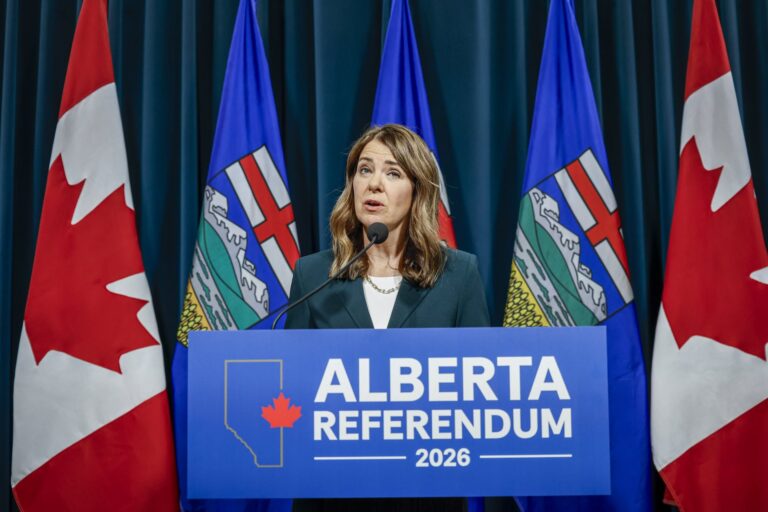
Alberta Premier Danielle Smith’s government revived the effort in 2023, commissioning a report that suggested the province could claim 53 per cent of the CPP’s assets, or $334 billion by 2027, if it decided to leave the federal pension plan.
But Trevor Tombe, an economics professor at the University of Calgary, and other researchers say Alberta’s estimate is significantly overstated. Tombe estimates the province could receive between 20 and 25 per cent of CPP assets, or $150 to $186 billion, based on this year’s figures—an interpretation broadly supported by Canada’s chief actuary, the federal government’s independent overseer of the CPP.
The dispute centres on the Canada Pension Plan Act, which says a province can withdraw from the fund with three years’ notice, but leaves room for competing interpretations of how much it would be entitled to receive.
Related Articles
Internal Finance Canada documents from June 2026 show that Ottawa is grappling with the same uncertainty. Canada’s chief actuary noted that the decades-old withdrawal formula over how CPP assets would be divided is “flawed” and has not kept pace with changes in how the CPP is funded and invested.
Alberta’s withdrawal from the CPP could increase pension contributions for Canadians in the rest of the country—excluding Quebec—according to pension experts. At the upper end of Tombe’s estimates, the CPP’s minimum contribution rate could rise by roughly half a percentage point, wiping out its financial cushion and requiring contributions to increase by at least 0.1 percentage point, about $180 per year for both workers and their employers. Further increases would depend on how much of a buffer policymakers want to maintain.
Those estimates assume Alberta leaves the CPP but remains part of Canada. If Alberta became an independent country, it would instead have to negotiate with Ottawa over how to divide pension funds and other federal assets and debts, Tombe said in an interview.
“I tend to think [a separate Alberta pension plan] is a risky thing because it creates political risk that doesn’t exist within the CPP, ” he said. In his paper, he argued that a provincial plan would offer less protection against regional economic downturns.
Alberta’s withdrawal from the CPP could also discourage international investments in Canada at a time when the federal government is seeking to attract more foreign capital, said Patrick Imbeau, technical adviser at the Public Service Pension advisory committee. The uncertainty could undermine Canadians’ confidence in the CPP’s ability to pay retirement benefits, even if the fund remains financially sound, he said.
Canada Pension Plan Investment Board spokesperson Frank Switzer declined to comment on how an Alberta withdrawal could affect the fund’s investment strategy, redirecting questions to Finance Canada. The chief actuary of the Office of the Superintendent of Financial Institutions also referred questions to the department.
In a statement to The Logic, Marie-France Faucher, deputy spokesperson for the Department of Finance, warned a withdrawal could mean “years of costly economic uncertainty,” while leaving Albertans without the same economies of scale and investment advantages the national plan offers. She said that the chief actuary’s work to determine how much Alberta could receive is still ongoing.
Transferring Alberta’s share could leave CPP Investments managing a significantly smaller pool of assets, including holdings that are difficult to sell quickly. As of March 2026, real assets such as infrastructure and real estate accounted for 20 per cent of its $793.3 billion portfolio, while government bonds made up 13 per cent and credit investments nine per cent.
“This is like a divorce, but scaled significantly bigger,” Imbeau said. Establishing a separate pension plan would impose significant administrative and staffing costs on Alberta, he said, potentially weakening both its own plan and the CPP.
A central argument in Premier Smith’s push for a separate pension plan is that Albertans contribute more to the CPP than they receive in benefits, because of the province’s younger population and higher earnings.
Tombe’s 2024 research estimated that an Alberta Pension Plan would require a minimum contribution rate of 8.2 per cent, compared with 5.9 per cent in the report commissioned by the Alberta government.
Both estimates were below the CPP’s minimum contribution rate of roughly 9.5 per cent, but Tombe’s analysis suggests the savings for Albertans could be considerably smaller than the provincial government’s projections.
Those savings would also depend on continued population growth. He estimated that nearly two-thirds of Alberta’s pension advantage could disappear if the province stopped attracting new residents.
Bill Robson, a former CEO of the C.D. Howe Institute who studied the case for a separate Alberta pension plan more than two decades ago, advises against rewriting federal legislation to clarify how CPP assets would be divided, arguing that doing so now could inflame tensions between Alberta and Ottawa by creating the perception that the federal government was trying to shortchange the province.
“The best stance for the rest of Canada is probably to take advantage of the ambiguity, go into negotiations, and try and avoid anything that is going to just turn the heat up under the separatist plot even higher.”
The CPP withdrawal proposal faces resistance among Albertans. An April 2026 Leger poll found that 55 per cent opposed establishing a separate provincial pension plan, compared with 30 per cent who supported it. But Imbeau says he believes the issue will remain on the table even if voters reject taking steps toward independence on Oct. 19.
“I don’t see it going away anytime soon because it’s popular with their [separatist] base… I see it as them trying to give themselves leverage in discussions with the federal government.”