Listen Now
0:00
As a former central banker, Prime Minister Mark Carney knows that markets can be a policymaker’s friend. Tell traders where you intend to go and they’ll beat you there. That’s why the interest rates that you and I pay had already risen when the Bank of Canada increased the benchmark rate last week. Investors bet that a central bank obsessed with inflation would have little choice but to respond to triple-digit oil prices with higher rates.
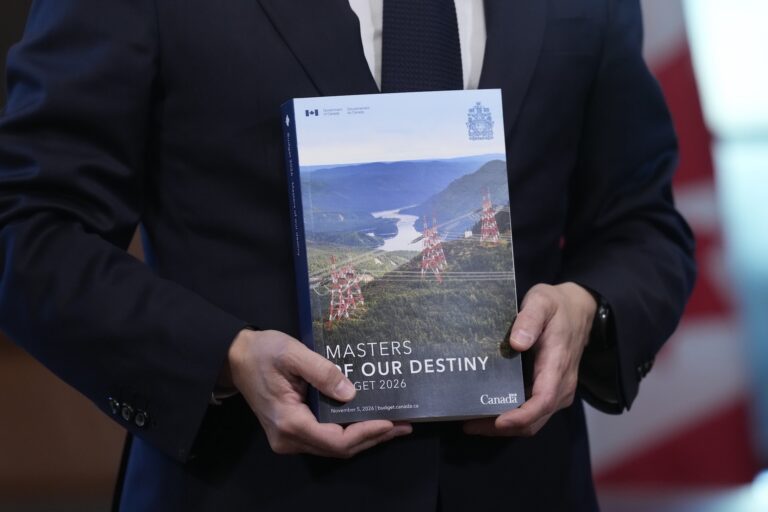
Carney will also know that such sorcery has its limits. Every so often you have to show investors that you mean what you say. With his second budget, Carney did that. Facing the most hostile bond market in memory, he and Finance Minister François-Philippe Champagne sent Canada’s creditors a message. They stuck to their fiscal anchors and used a significant portion of a revenue windfall on measures that should create the kind of sustainable economic growth that will make Canada’s growing debt load manageable.
“Unlike what we are seeing in other advanced economies, Canadians—not the bond market—will determine our choices,” Carney and Champagne wrote in a foreword to the budget.
Related Articles
The bond market might see things differently. Everyone’s borrowing costs have risen because of inflation, but the yields on Canadian bonds are significantly lower than countries such as the U.S., the U.K and France. We know why. Each of those nations has tested the patience of their creditors by demonstrating a disregard for responsible fiscal policy. The Bank of Canada reckons that most of the increase in British and French yields is the result of higher “term premiums,” the extra yield that investors demand to cover the risk that countries might default on their debt.
Carney is attempting a historic overhaul of the Canadian economy while trying to manage widespread anxiety over the cost of living. But maybe the most important thing he needed to do with his second budget was signal that he doesn’t take his credibility with investors for granted.
The chaos in France is a cautionary tale of what happens when day-to-day spending swamps investment in things that make an economy stronger. Not so long ago, yields on French 10-year debt were lower than that of Canada. Now, they are more than a percentage point higher, leaving France’s government to cope with a societal crisis and a budget crisis simultaneously.
“Let’s not be like France,” Bank of Canada governor Tiff Macklem told the House of Commons finance committee this week.
Read more of our federal budget coverage
Canada prides itself on being the “cleanest dirty shirt” in a world where the International Monetary Fund projects that global public debt is headed to 100 per cent of gross domestic product by 2030. Canada’s boast isn’t quite true. The Bank of Canada’s research on term premiums shows that creditors are demanding about the same amount of extra cover from the government of Canada as they are from Donald Trump’s America, where the federal deficit is about six per cent of gross domestic product, compared with about two per cent in Canada.
Germany, meanwhile, pays almost no term premium, according to the Bank of Canada. As a result, it has become the benchmark among rich economies. That’s not an argument for German-style austerity, but it does mean that if Carney wants to push fiscal responsibility as a Canadian advantage, he’ll have to work harder to show that his borrowing is intentional.
The budget met that test. Because Canada is a net exporter of energy, triple-digit oil prices triggered a revenue windfall. Carney and Champagne spent a lot of it, but they resisted the urge to push their luck. The deficit in the fiscal year that ended on March 31 will be 1.2 per cent of GDP, compared with an estimate in the spring of 2.1 per cent. It will widen to 1.8 per cent of GDP this fiscal year and the following one, in line with previous forecasts.
Federal debt as a percentage of GDP will hover around 40 per cent for the next five years, an improvement on the previous forecast that had it closer to 42 per cent.
Bond markets should be able to live with that, in part because Carney and Champagne intend to use some of their windfall on measures that should ignite economic growth. The previously announced Mega Productivity Deduction and a new break on capital gains that are invested in Canadian companies will cost the federal treasury some $52 billion over five years. The government announced affordability measures worth some $30.7 billion, including $11.2 billion for an ambitious pledge to end homelessness in a decade. That spending will do little to address the productivity crisis, but it might buy some political stability. No government could ignore the cost of living when polls consistently show it ranks as voters’ greatest concern.
There will be questions about the spending plan. Much of Carney’s spending is off-budget, as he’s chosen to classify anything that could boost economic growth as capital spending. Carney sees that as “good debt,” but some critics just see it as “more debt.” The federal government’s liabilities are set to rise by more than $800 billion over the next five years, pushing net debt to almost $2 trillion by 2030.
There’s nothing nefarious about that; the numbers are there for everyone to see. It’s a bet by the prime minister that he can convince bond markets to back an industrial policy that exceeds the ability of taxpayers to finance. Given his background, Carney has a lot of credibility with creditors, but not so much that he can get away with whatever he wants. He’ll need to be careful.
Kevin Carmichael is The Logic’s economics columnist and editor-at-large. He has spent more than two decades covering economics, business and finance for outlets including Bloomberg News, The Globe and Mail and the Financial Post, where he also served as editor-in-chief.