Listen Now
0:00
“Where is Monsieur Willie Gagnon?” a shareholder asked at TD’s annual general meeting in April, after noticing that the longtime face of the Mouvement d’éducation et de la défense des actionnaires (MÉDAC) was missing.
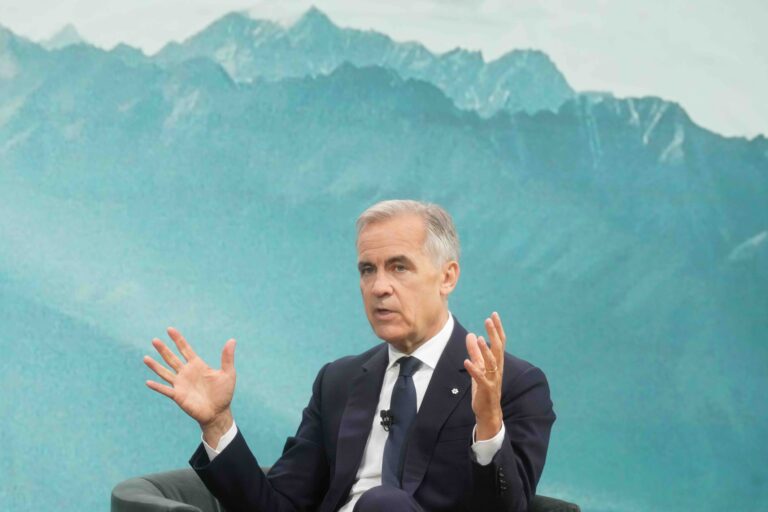
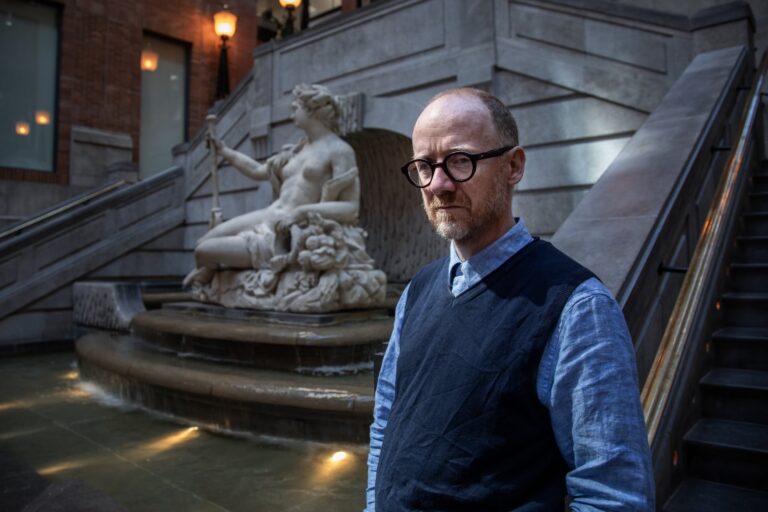
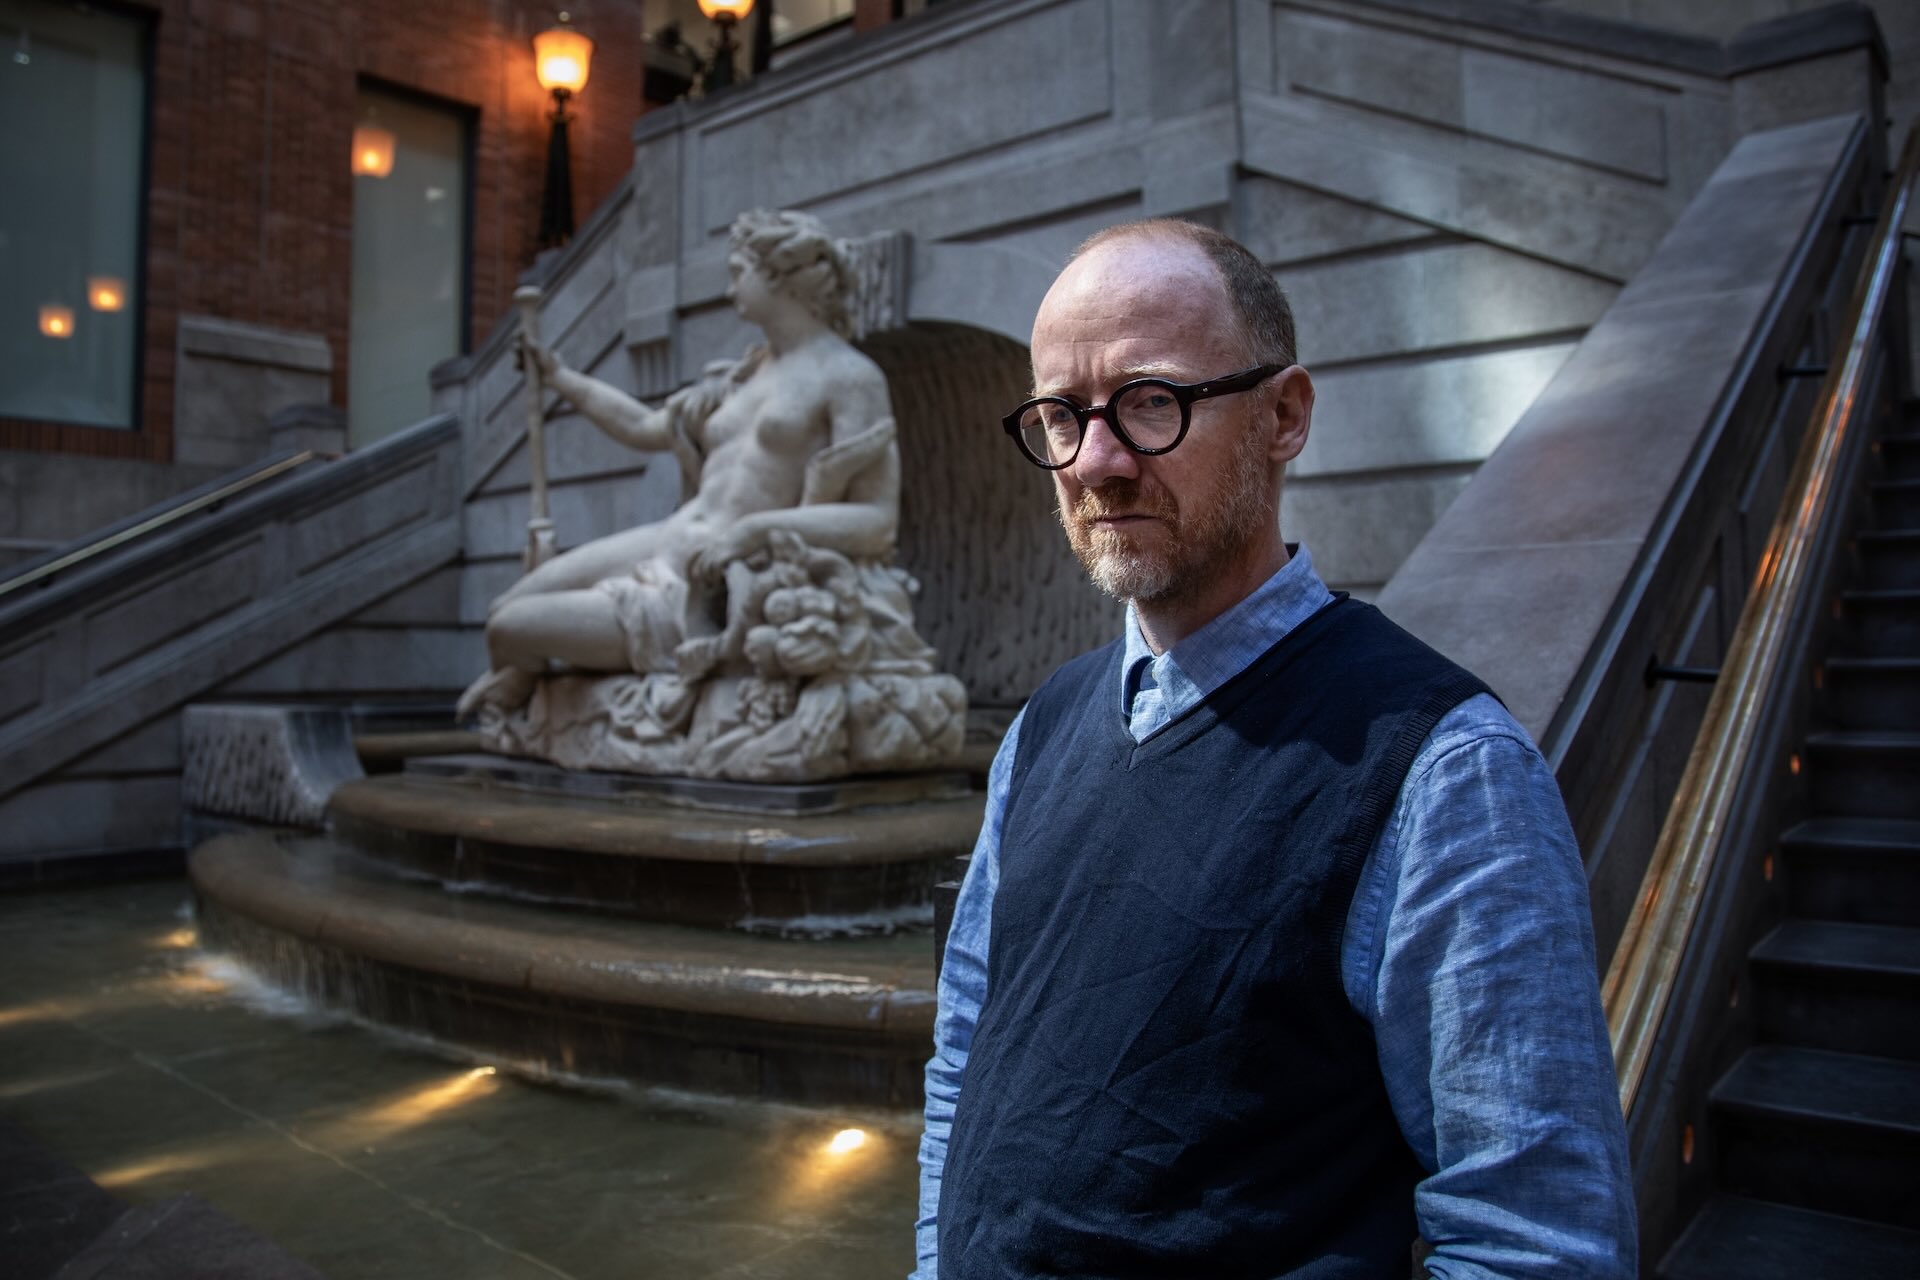
Gagnon was at CIBC’s overlapping AGM down the block. For nearly two decades, the 52-year-old was a fixture of Canada’s proxy season, pressing executives on issues like executive pay, board diversity and climate policy. The shareholders considered him one of the more interesting voices at the bank’s meetings.
Next year, however, Gagnon won’t be taking the microphone. After roughly 400 annual general meetings, Gagnon is leaving shareholder activism, with his executive director role at MÉDAC now abolished.
Talking Points
- Willie Gagnon spent 19 years leading the Mouvement d’éducation et de la défense des actionnaires (MÉDAC), attending roughly 400 annual general meetings during his tenure
- Several shareholder advocacy groups have shut down in Canada this year, while major banks have continued to scale back some of their climate commitments
Originally from Saint-Mathieu-d’Harricana, Que., Gagnon regularly appeared before Senate committees and at annual meetings, where he addressed executives exclusively in French.
“I feel like I’ve covered the important issues that are likely to keep coming back,” Gagnon told The Logic in an interview. He said he had grown tired and felt he had taken many of those battles as far as he personally could.
The fatigue, he said, extends beyond him: Canada’s shareholder-activism community is shrinking, longstanding groups are disappearing and corporate resistance is hardening.
Related Articles
The country has seen a number of shareholder groups dissolve this year. In June, Quebec-based Regroupement pour la responsabilité sociale des entreprises (RRSE) permanently closed after more than 25 years of advocacy on corporate responsibility. Investors for Paris Compliance, a group that had pressed financial institutions to align their activities with climate commitments since 2021, ceased operations in May, saying it believed “investor accountability has reached its limits.”
“The resources necessary to lead these types of fights are not infinite. We [at MÉDAC] weren’t exactly rolling in money, and that is the case for all organizations that make shareholder proposals,” Gagnon said, adding that he’d been MÉDAC’s sole employee since joining in 2007.
The financial pressure on advocacy groups is unfolding alongside a shift in the priorities of some of the companies they target.
All of Canada’s largest financial institutions are scaling back their climate commitments. TD, BMO, National Bank and CIBC withdrew from the Net-Zero Banking Alliance in January last year. In April, RBC and Scotiabank lowered their 2030 financed-emissions targets for several carbon-intensive sectors, citing changes in government policy, energy demand and the slow development of carbon capture technologies.
Gagnon said he has observed a shift in corporate Canada since the start of U.S. President Donald Trump’s second term, describing a “cooling” in relations between advocacy groups and corporate boards. While companies remain willing to engage, he said they have become more resistant to activist demands, particularly on environmental and governance issues.
He linked the shift to Canada’s economic reorientation amid the U.S. trade war and broader economic uncertainty, pointing to the federal push to remove interprovincial trade barriers, expand fossil fuel exports and diversify trade as factors driving the change.
“If we want to establish an energy corridor, we will have to violate certain principles we held previously that prevented us from doing so,” he said. “The interest of big Canadian corporations in their company’s development is now based on different principles, and that made our life more difficult.”
Shareholder activism has significantly transformed since Gagnon’s early days. When he started, MÉDAC was more openly confrontational; at annual meetings, the group would spend hours challenging management. That’s since given way to more professional, constructive rapport, he said. Corporations now anticipate the group’s presence, often dispatching the same secretaries or legal counsel year after year to maintain a steady, ongoing dialogue.
For small shareholders, Gagnon said, filing a proposal is often the only real leverage they have with a large company. Whether a proposal gains traction often depends on support from Canada’s largest institutional investors, who can use the weight of their holdings to influence management.
Among Gagnon’s proudest accomplishments at MÉDAC was the push to preserve in-person annual meetings after the COVID-19 pandemic. He also pointed to greater disclosures around executive compensation and increased representation of women on corporate boards as areas where shareholder pressure helped drive change. Executive pay, however, remains a problem, rising “de manière folle,” or “in a crazy way,” he said.
MÉDAC submitted the vast majority of shareholder proposals during the 2026 proxy season at Canada’s Big Six, all of which were defeated. Nonetheless, Gagnon said a proposal does not have to win a vote to have an impact. Companies often negotiate with shareholders before an annual meeting because they would rather avoid a public vote that could expose meaningful opposition to management, he said.
Even as proposals fail at the ballot box, the issues reaching bank boards are evolving.
Gagnon sees AI governance as one of the next major battlegrounds. MÉDAC filed proposals urging companies to adopt a voluntary federal framework to address risks including AI bias, hallucinations and weak oversight. Companies generally told Gagnon they preferred to wait for the then-forthcoming federal policy rather than adopt a framework they said was not designed for them.
Canada tends to “take its time” rather than lead on governance reform, Gagnon said, and he would like to see regulators take a more active role. He said securities regulators—rather than corporations themselves—should determine whether a proposal can be excluded, arguing that the country’s relatively small volume of proposals makes this approach manageable.
As for what’s next, Gagnon, who became a father in recent years, wants to focus on his family life before pursuing other opportunities. MÉDAC said in a statement its board has put measures in place to ensure continuity following his departure.
Shareholder activism hasn’t reached its limit, Gagnon said, but its approach may need to change. He envisions a model of governance that goes beyond traditional shareholder meetings toward something resembling European stakeholder assemblies, where employees, customers, communities, governments and shareholders take a greater role in decision-making.
“The [shareholder advocacy] movement has to think about not its relevance, but its existence. How are we going to continue the fight to defend shareholders where they are now?”