Sponsored Content
The road to risk-smart regulation
How to evolve the rules governing Canada’s financial sector to better balance protection with innovation
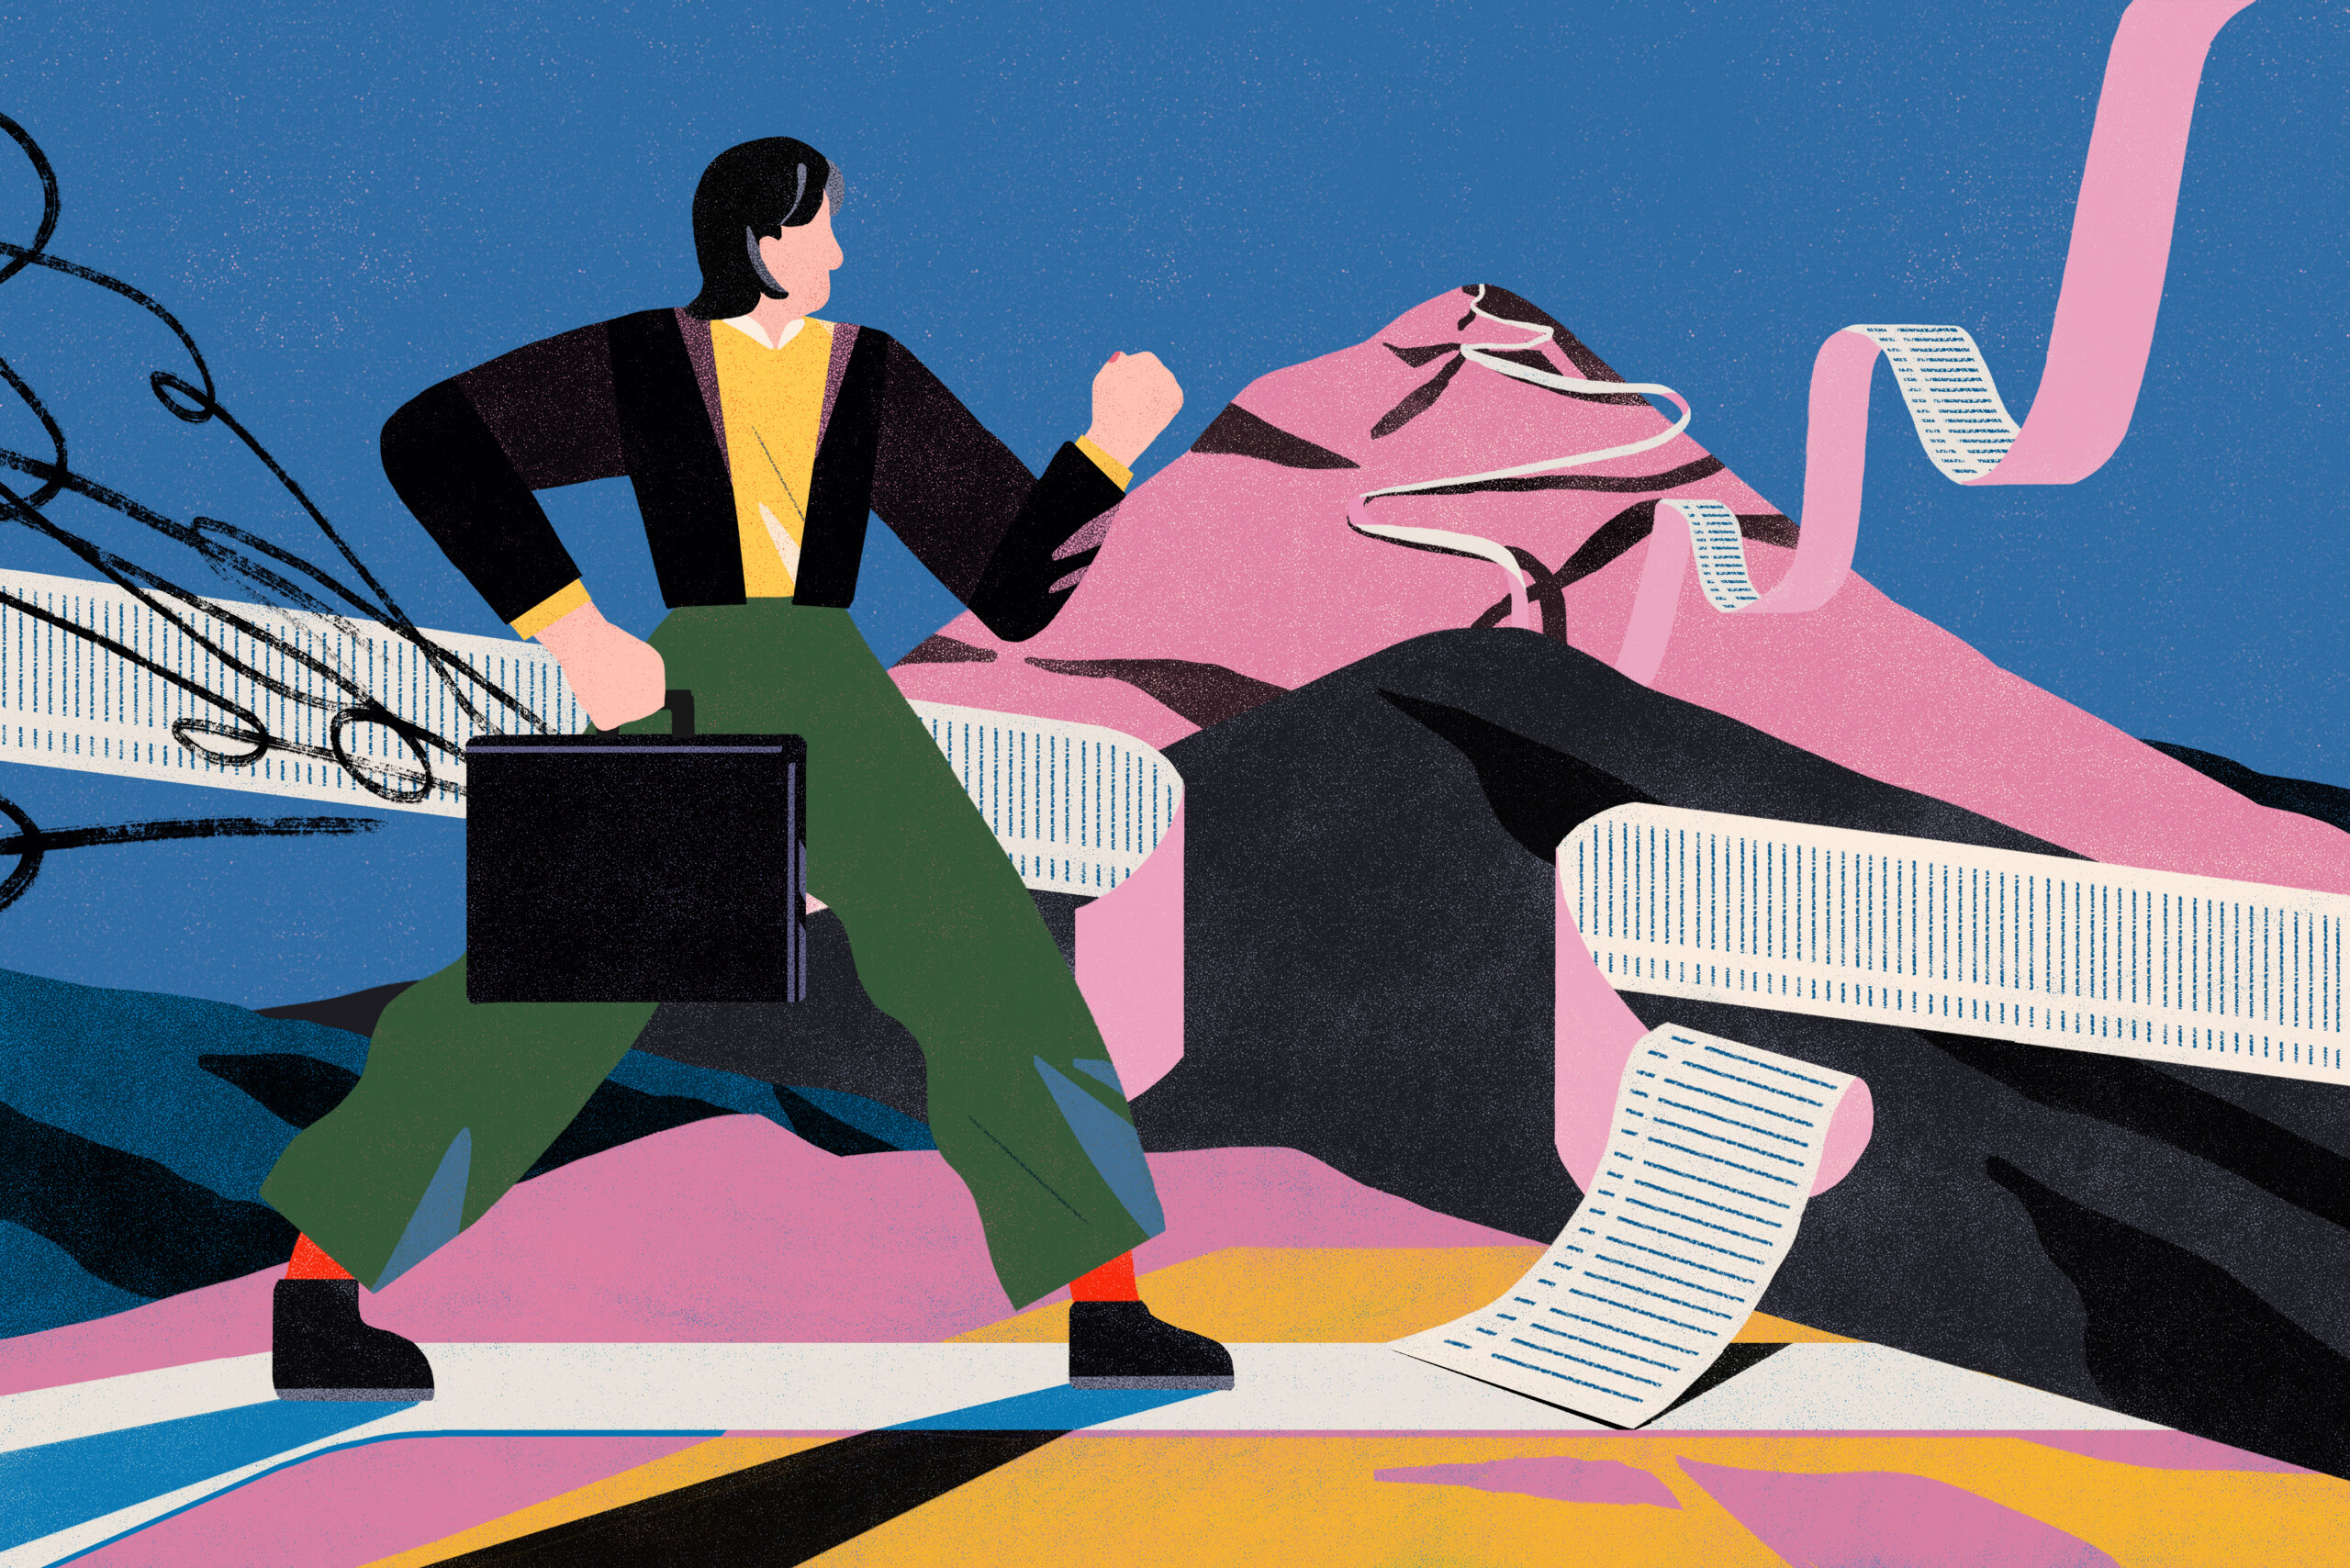
Illustration by Paul Kim
Sponsored by:
Sponsored by:
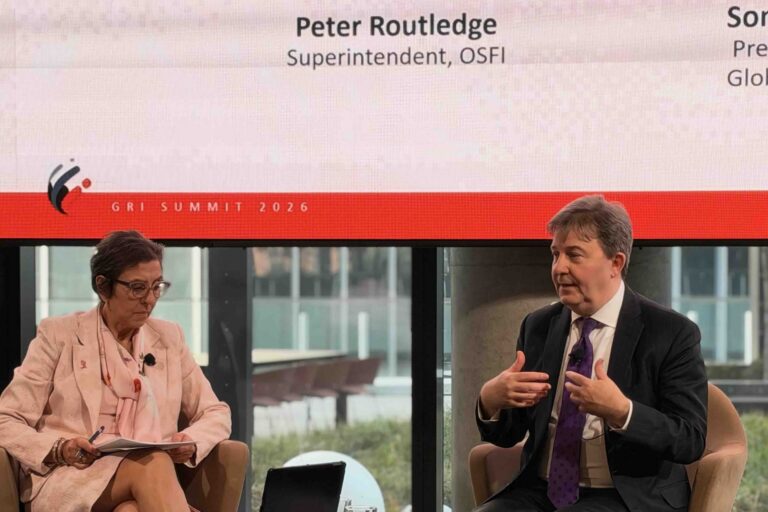
In September, in an Economic Club of Canada speech, Office of the Superintendent of Financial Institutions (OSFI) head Peter Routledge put forward a new approach to regulating one of Canada’s largest and most consequential economic sectors. Citing emerging threats, including shifting global economic dynamics and evolving digital capabilities, Routledge declared an imperative to update the stability-centric status quo. “We at OSFI are shifting our risk appetite so that we avoid the stability of the graveyard without accepting too much financial instability risk,” he said.
For a country whose financial regulations have long prioritized prudence above all else, Routledge’s remarks signal a noteworthy shift. “We may be at a turning point in regulation in Canada,” says Anthony Ostler, President and CEO of the Canadian Bankers Association.
For many observers, change is overdue. “Our regulatory framework has long been too risk-averse,” notes Ian Lee, an Associate Professor of Management at Carleton University’s Sprott School of Business, and a former commercial banker.
Yet few believe the strategy should be throwing caution to the wind. Rather, many experts contend that the financial industry, and the economy as a whole, would be better served by a regulatory environment that strikes a smarter balance between protection and growth.
The question is: What might that look like?
Related Articles
Why change is needed
Any discussion about the future of financial regulation in Canada must begin with a clear-eyed understanding of the current regime.
Here’s what works: Thanks to high capital-requirement thresholds for banks, ample buffers to hedge against incorrect models, and floors to avoid unduly discounting risk-weighted assets (among other measures), the country’s regulatory environment has proven resilient against global shocks that rocked nations with more laissez-faire rules, such as the 2008 crisis and the dot-com bubble. Globally, our financial institutions punch well above their weight on safety and soundness. Canadians hold more trust in their banks than any of their G7 peers.
“Canada is starting from a position of strength,” says Peter MacKenzie, a Senior Policy Analyst at the C.D. Howe Institute. MacKenzie who co-leads its Financial Regulatory Excellence Initiative, which publishes an annual scorecard measuring the effectiveness of and gaps within financial regulation in Canada. And in his view, the limits of the current system are abundantly clear: “We’re seeing that increased regulatory burden doesn’t necessarily decrease the likelihood of a recession, and can in fact have an associated negative effect on growth.”
Which leads us to what works less well. The system is sprawling: When you tally up federal, provincial and territorial organizations overseeing banking, securities, insurance, pensions, and credit unions, financial institutions in Canada are subject to the rules of 44 regulatory bodies, creating a heavy burden of compliance for even well-resourced organizations. It’s not conducive to agility, nor new entrants: Consider the five years it took what’s now known as Tru Cooperative Bank (formerly First West Credit Union) to complete the continuance process allowing it to operate as a federal institution, or the more than six years online brokerage Questrade spent pursuing a bank license. And the rules can be inconsistent: For example, while banks in Canada are regulated at the federal level, payment service providers (PSPs) generally fall under provincial jurisdiction, meaning a consumer who pays a bill online using bank infrastructure has different protections than someone paying via a non-bank PSP.
None of this complexity is by design: “It’s a really honest attempt to do right by Canadians,” observes Todd Roberts, a Senior Partner of Strategy, Risk, and Transactions at Deloitte Canada, where he leads the firm’s Canadian payments practice and co-leads its global payments practice. (Roberts previously worked for seven years as a Senior Vice President at CIBC, where he led enterprise payments and innovation.) “But the accretion of many additions from many different parties over many years means there isn’t always the coherence you see when you’re building regulation from scratch, like we saw with the recent Stablecoin Act.” He adds that the scope and complexity of financial regulatory compliance discourages needed advancements in productivity, innovation, and competitive position.
A new balance is therefore, in Roberts’s view, sorely needed. “We’ve historically been very defensive, but this is a time to play more offense,” he says. “It’s about creating the conditions that allow Canadians to thrive, rather than simply be protected.”
How reform might work
Experts say a few practical reforms to Canada’s financial regulatory ecosystem would strike a more productive balance between protection and risk, and help level the playing field between incumbents and new entrants.
First, many would like to see regulators formally adopt secondary mandates related to growth, competitiveness, and/or performance, as their equivalents in Australia and the U.K. have done in recent years. As it stands, most Canadian regulatory bodies are accountable solely to the directive to protect, which Ostler says can lead to tunnel vision: “If you give a very specific set of requirements to a regulator, they will take that to perfection, but they will also take it out of context,” he says. He points to Canada’s anti-money-laundering reporting process, where the burden of registering a suspicious transaction is onerous, and where actual seizure and conviction rates remain low. “It’s a compliant system, but I’d be surprised to hear anyone say we have an effective system,” he says. “There’s a huge opportunity to improve this.”
A secondary mandate that explicitly ties the work of regulators to beneficial economic outcomes might not have been necessary in the years when both per-capita GDP and productivity were on a steady uptick, but with neither metric at all a given any longer, experts say there’s merit in codifying a commitment to growth.
Second, observers say greater clarity about regulations coming down the line, similar to regulatory initiatives grids in the U.K. and Australia, would lighten the onus of compliance for organizations. “Firms can see what’s coming down the pipeline a year out or even further,” explains MacKenzie. “That helps them coordinate and set up plans in advance.” While some regulating bodies in Canada, including OSFI, regularly publish their own policy plans, there is no coordinated or standardized forecast for the sector.
Ostler points out that an overarching regulatory initiatives grid would provide the predictability organizations need to take bigger swings, while also providing peace of mind to potential investors. “Often things are presented almost as a fait accompli,” he notes. “It would be very helpful to have more transparency.”
Finally, experts would like to see more accountability baked into the system. Many champion the idea of cost-benefit analyses of all new and existing regulations, similar to the approach used in the U.K., where a dedicated panel (comprising senior financial industry leaders and experts) advises regulators on the efficacy of policy initiatives. There are sporadic examples of this in Canada, but MacKenzie believes a more rigorous overarching process for vetting the pros and cons, incorporating different perspectives, is sorely needed. “We see real benefit in a concrete, and public, cost-benefit analysis process that regulators, industry, and the general public can all look at to judge a new regulation,” he says. “It would change the conversation from ‘Here’s a risk, we need a regulation’ to ‘Here’s a risk, we could add a regulation, but what would be the knock-on effects that might come from it?’.
For his part, Lee believes cost-benefit analyses with industry input would result in more nuanced and effective policy. “It would be an important step forward for our regulatory environment,” he says. “It would also help ensure periodic reviews to find out which of the regulations are working and which ones are not.”
A better balance
Given the size and scope of Canada’s financial sector, few expect wholesale regulatory reform. It may not even involve fewer rules. As Carolyn Rogers, Senior Deputy Governor of the Bank of Canada, told the House of Commons Standing Committee on Finance late last year: “You want to be careful when you remove regulations. Usually they’re there for a reason, but they certainly can always be reviewed and made efficient.”
But there’s little doubt of the need for financial regulation capable of meeting the competitive needs of a rapidly evolving industry. “As the system gets more complicated, and as things move faster on the technological side, I think we’ll have to learn how to adapt and make changes quicker in our regulatory environment,” MacKenzie reasons.
Roberts shares this view. “We have a tendency in Canada to think about things, study them, and make calm, calculating decisions. It’s in our DNA,” he notes. “But I think we need to be willing to be a bit more confident and a bit less concerned. As a country, we’re more often right than we are wrong. And I’d rather see us be willing to take a few more risks, and be a bit more agile, because that is what the next decade is going to require from us.”
This content was paid for and directed by The Canadian Bankers Association and was produced independently of The Logic’s newsroom in consultation with the advertiser. You can read our policies on advertising, sponsorships and partnerships here.
Loading...
Thanks for sharing!
You have shared 5 articles this month and reached the maximum amount of shares available.
CloseThis account has reached its share limit.
If you would like to purchase a sharing license please contact The Logic support at [email protected].
CloseGift the full article!
You have gifted 0 article(s) this month and have 5 remaining.
Recipients will be able to read the full text of the article after submitting their email address. They will not have access to other articles or subscriber benefits.